featured insights & webinar
The recent sell-off in China’s new-economy sector exposes a sharp disconnect between market sentiment and robust operational fundamentals. Despite 'de-CATLization' fears drove steep valuation corrections, CATL expanded its market share, anchored by global scale, brand equity, and a high-margin energy storage business. Beyond batteries, global biotech licensing breakthroughs and localized AI hardware demand provide powerful tailwinds across innovative segments in China. Meanwhile with the premium in CATL-H over A-share, CATL-A which Premia China New Economy ETF allocates to, has also become one of the few if not only overweight-rated stock in Chinese battery universe for most analysts and allocators while CATL-H being neutral-rated. In this article, we discuss how, with valuations compressed, current level of Premia China New Economy ETF offers a timely entry point to accumulate market leaders on weakness.
Oct 23, 2026
AI development between the US and China have taken very different paths. While the US has been prioritizing frontier foundational models, and cutting edge computing power funded by massive private sector capital from global investors, China focuses on taking AI as next generation productivity driver, and emphasizes diffusion, industrial automation, robotics as embodied AI and low-cost open-weight models to drive productivity and economic growth with strong policy influence. This distinction is important in understanding the trajectory of China’s development, and why as investors looking to position for global AI opportunities, the leading cohort in China’s STAR Board where the country’s hard tech leaders converge is increasingly more relevant. In this article, we discuss the background of China’s STAR Board, its leading constituents across China’s emerging hard tech sectors, how the policy tailwinds under China’s 15th Five Year Plan have fast tracked their earnings growth, and the dynamics behind the outperformance of Premia China STAR50 ETF which was up +18% year-to-date compared to offshore China tech which have delivered lacklustre performance as Hang Seng Tech, Overseas China Internet and MSCI China were down between 12-30% during the period.
Oct 07, 2026
Taiwan has emerged as a key beneficiary of the global AI investment cycle, delivering exceptional equity returns while remaining under-owned by international investors notwithstanding the fact that it has already become the largest market within MSCI Emerging Markets. Strong GDP growth, exports and earnings, alongside relatively attractive valuations, provide a solid fundamental backdrop. While TSMC remains the cornerstone of Taiwan’s AI ecosystem, the opportunity extends a broad range of companies spanning foundry, advanced packaging, substrates, networking, power and thermal management, and many are in fact the most leading global manufacturers in critical nodes of the AI and advanced technology supply chain. In this article, our Partner & Co-CIO David Lai discusses such dynamics and drivers behind the outperformance of our Premia FTSE TWSE Taiwan 50 ETF as the tool to capture opportunities in the broader AI value chain opportunities far beyond TSMC alone.
Sep 04, 2026
Onshore Chinese stocks rallied in Q2, as geopolitical anxieties gave way to greater optimism—along with falling energy prices—and AI exuberance continued to support stocks in the global hardware supply chain. Beneath the broad market gains, however, it was a ‘tale of two economies’, as optimism toward tech balanced out a less sanguine view of China’s domestic economy. In this article, Dr. Phillip Wool, Global Head of Research of Rayliant Global Advisors, discusses the macro and factor-level influences of China A share performance in Q2 2026, and given the diversified nature of China’s broad market, it offers a relatively attractive profile for investors in longer-term growth for not only hard tech but broader new economy growth opportunities.
Aug 07, 2026
The Fed's abrupt turn — from rate cuts at the start of the year to a looming hike — has caught many investors off guard. Longer-duration US Treasury strategies have slipped into the red since the war in Iran erupted, as the economy shifted from a supply-side, oil-driven inflation shock to broadening price pressures compounded by a slew of Trump administration policies since 2025. New Fed Chair Kevin Warsh's FOMC has struck a hawkish tone, stripping the market of any lingering hope for a continued easing path. Yet his task is far from straightforward: unlike 2022, this cycle would begin from an already elevated rate plateau rather than near zero — meaning considerable stress is arguably baked into the system before a single hike lands. In this article, we discuss why Floating Rate Notes (3077 / 9077 / 9078 HK) looks increasingly well-timed for investors seeking to derisk by harvesting an elevated, weekly-resetting coupon with effectively zero duration and collecting front-end carry, while longer-duration fixed-rate Treasuries continue to absorb losses at the long end.
Jun 30, 2026
China’s hard-tech sector is entering a new phase of structural growth, driven by AI adoption, semiconductor localization, and strong policy support. Domestic hard-tech leaders across semiconductors, optical networking, advanced manufacturing, and memory technologies have significantly outperformed broader Chinese and offshore equity markets year-to-date, while a new IPO wave led by ChangXin Memory Technologies (CXMT), Unitree Robotics, and other strategic technology champions are set to further enrich the STAR Market ecosystem. In this article, our Partner & Co-CIO David Lai discusses that our Premia China STAR50 ETF and Premia CSI Caixin China New Economy ETF offer targeted access to companies benefiting from China’s long-term technology and industrial transformation.
Jun 12, 2026
The complex macro picture has played squarely to the strengths of Premia's fixed income range, with every ETF in the lineup outperforming its mainstream investment grade (IG) and high-yield (HY) peers over the past six months. On the IG side, a constrained Fed pushing US long-end yields toward 5% makes a strong case to hold shorter duration bonds —while accommodative China liquidity and firm local demand underpinned Asia credit—drove the relative gains than the broader global IG universe. On the high-yield side, the Premia China USD Property Bond ETF significantly outperform the US and Asia HY peers along with the gradual recovery of China's property market, and has more than 660bps of spread still on offer for further compression toward the regional average. In this article, we explore how as this trend persists, the modular lineup offered by Premia's fixed income ETF range is increasingly turning today's fragmented macro environment into clear relative outperformance across both rating tiers.
Jun 12, 2026
Even if a peace deal is achieved soon, the writing is already on the wall for the US economy. Higher inflation and rates/yields appear inevitable. The double shocks of the Trump tariffs of 2025 and now the Iran War will exacerbate the inflation already working its way through the supply chain. In this article, our Senior Advisor Say Boon Lim discusses why as US equity valuations appear increasingly mispriced, with current multiples severely challenged by a rising discount rate, Asian emerging markets are gaining recognition as a resilient alternative. China's exit from deflation is emerging as a positive signal in particular, as improving earnings growth prospects and technological development could together present a compelling alpha opportunity.
May 21, 2026
As Iran conflicts closed off the Strait of Hormuz and sparked the ongoing oil price shock, global equity saw abrupt drawdown in Q1 as geopolitically anxious investors turned risk-off and quickly adjusted portfolios. Amidst that heightened volatility, contrary to broad market correction across both onshore and offshore Chinese equities, the Premia China Bedrock Economy strategy flourished, while the Premia China New Economy and Premia China STAR50 managed to get through the quarter nearly unscathed and remain well-positioned for policy tailwinds and hard tech structural growth as the 15th Five-Year Plan kickstarted. In this article, Dr. Phillip Wool, Global Head of Research of Rayliant Global Advisors, discusses about the macro and factor-level backdrop of China A share performance in Q1 2026, and drivers for continued optimism for onshore equities this year.
May 12, 2026
With US technology stocks under pressure from high valuations and risk-off sentiment from high beta trades amid heightened global market volatilities given geopolitical tensions, China advanced tech sector offers a well-supported and timely alternative for investors looking to diversify. The numbers speak for themselves: over the past two years, the hardcore technology focused STAR50 Index gained 77.3%, comfortably ahead of the Nasdaq's 40.2%. China has put innovation at the core of its long-term growth plan, with strong government backing for AI, semiconductors, and advanced manufacturing. Under Beijing’s domestic substitution policy, Chinese companies are rapidly replacing foreign technology with homegrown solutions, and earnings forecasts are being revised higher. In this article, our Partner & Co-CIO David Lai discusses the policy signals emerging from China's 15th Five-Year Plan and explores how investors can tap into these opportunities through our Premia China STAR50 (3151 / 9151 / 83151 HK) for focused exposure to China's leading hardcore technology companies, as well as our Premia China New Economy (3173 / 9173 HK) that provides broader coverage across nearly 300 holdings spanning the full new economy landscape.
Apr 08, 2026
BY TOPICS
Chart Of the Week
Michael Ng
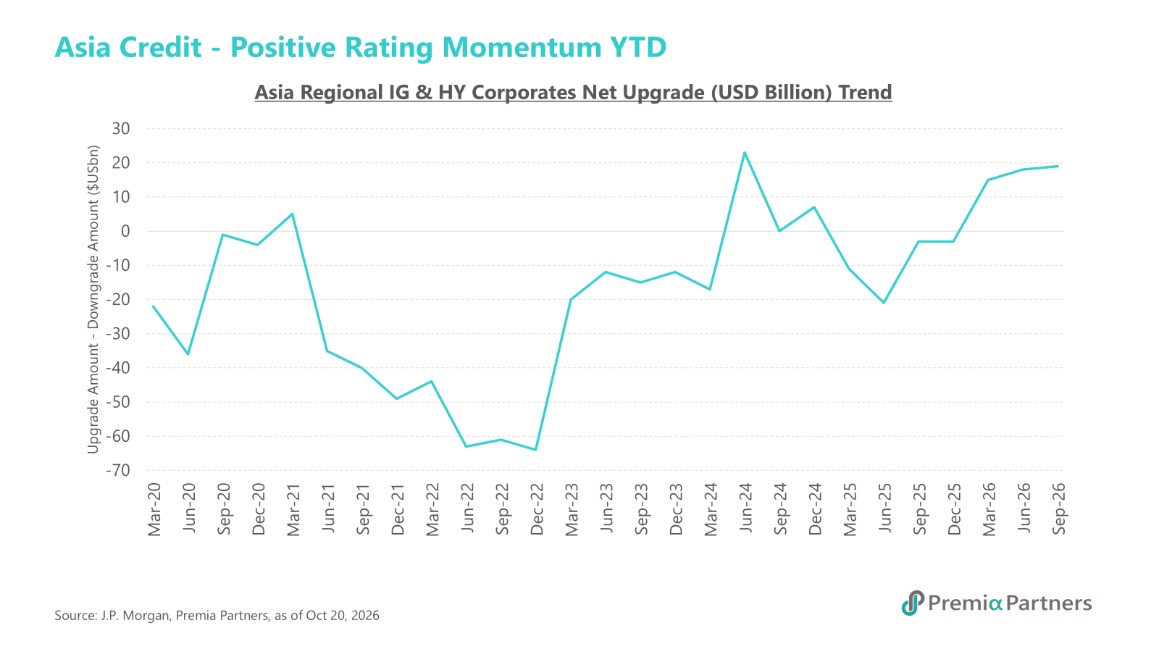
J.P. Morgan data show net rating upgrades for Asian investment grade (IG) and high yield (HY) corporates (by debt amount) turning positive from March, reaching roughly US$19bn by September 2026. The improvement reflects firm corporate fundamentals: steady earnings growth, resilient macro conditions, limited default activity and disciplined primary supply. Meanwhile notwithstanding the equity shock triggered by MSCI consultation for potential reclassification of Indonesia from emerging markets to standalone status, reaction to its bond market has been much calmer with yields recovering soon after initial selloff. For Asian bond allocators, the next test of this trend would be the market receptiveness to step-up in borrowing by China's IG technology leaders amid concerns for massive AI debts in the US. Tencent raised about US$5.7bn last week across US$1.8bn of dollar notes and RMB26bn (US$3.9bn) of offshore yuan bonds, with the 10-year dim sum tranche priced at 2.40% against over 6% on the dollar notes. It was its second offshore deal this year after a US$4.7bn transaction in June, with proceeds reportedly directed largely at AI-related capex. Rating agencies have yet to react, but bond investors already have: despite global unease over AI monetisation and a semiconductor selloff, order books topped US$23bn, more than four times the deal size. Large debt raises would normally add leverage and weigh on ratings, but three factors suggest the risk is contained. Tencent's deals sit comfortably within its balance-sheet capacity even with capex expected to exceed RMB200bn (US$30bn) a year through 2027. Chinese big tech is also tapping equity and cheap offshore RMB rather than dollar debt alone and in a much more moderate scale compared to global peers: Alibaba raised HK$80bn (US$10.2bn) through a Hong Kong share placement in August, and the coupon gap Tencent secured has Meituan now considering a dim sum sale of its own. As for Premia J.P. Morgan Asia Credit Investment Grade USD Bond ETF (3411 HK) which covers a diversified basket of IG issues, the exposure is small relative to the asset class: in the corporates make up around 56% of the ETF but TMT less than 7%, leaving holders exposed to the broader upgrade corporate credit upgrade cycle with limited exposure to Chinese big tech issuance.
Oct 26, 2026